
Selling Privately? Why a Pre Sale Property Valuation Is Your Best Negotiating Tool
Picture this. You’ve decided to sell without an agent, you’ve listed the house online, and the first serious buyer comes back with an offer that’s about 10% under what you were hoping for. Is that a fair offer or a lowball? You don’t really know, and every number they throw at you feels like it’s coming from their side of the table.
That’s where a pre sale property valuation comes in. It won’t make the buyer pay more, but a detailed property valuation report can give you evidence to support your asking price, rather than relying on guesswork or a neighbour’s rumour about what the house down the road sold for.
This article explains what a pre sale valuation is, how sellers use it in negotiations, where it can trip people up, and when it might not be worth the cost.
Summary: Selling privately means you carry the pricing risk yourself, because nobody else is doing the market research for you. A pre sale valuation is an independent, written opinion of market value based on the property’s condition, location and recent comparable sales. It helps you set a realistic asking price, respond to low offers with evidence rather than emotion, and avoid the common trap where a buyer’s bank valuation comes in below the agreed price. It isn’t a guarantee of what the property will sell for, and it’s not always necessary, but for many private sales it’s one of the cheapest ways to protect yourself. Before you sign anything, get a clear picture of where the property sits in the market.
Why a Pre Sale Property Valuation Matters When You’re Selling Privately
When an agent sells a home, they bring the market knowledge, the marketing and the negotiating experience. When you sell privately, all of that falls on you. The pricing decision in particular can make or break the sale.
What a valuer actually does
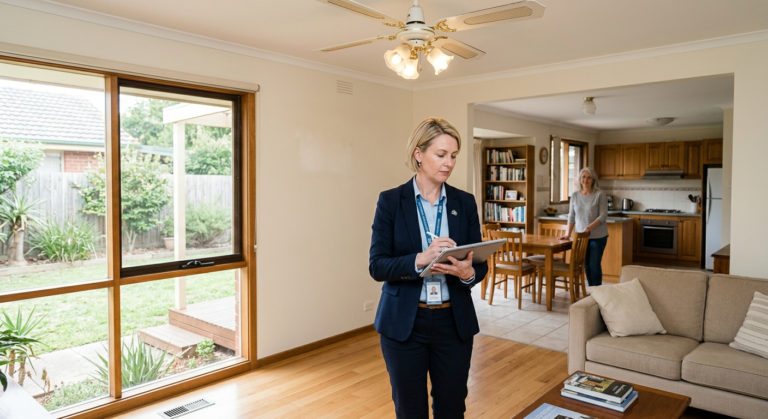
A pre sale valuation is a written opinion of market value. The valuer inspects the property, looks at its size, layout, condition, features and position, and then compares it with recent sales of similar properties nearby. They’ll usually provide a figure, or a range, along with a report explaining how they reached it.
Most valuers will also consider factors that can influence a property’s value, such as a dated kitchen, a sloping block, a noisy road, higher-than-average strata levies, or planning restrictions on what can be built. These are the details buyers pick up on during negotiations, so it helps to know them in advance.
How it differs from an agent’s appraisal
Real estate agents often offer a free appraisal, and it’s worth having one. But an appraisal is usually a sales estimate tied to getting the listing, and the agent’s fee depends on the sale price. A valuation is a professional opinion prepared for the owner, and the valuer’s job is to give an independent view of value.
Neither is perfect, but having both gives you a much better sense of where the property sits.
Where a Valuation Gives You an Edge in Negotiations
This is where most private sellers feel the benefit. A good valuation changes the conversation from “what do you think it’s worth?” to “here’s what the evidence says.”
Setting a price you can defend
If you list too high, you’ll get few enquiries, and buyers will start wondering what’s wrong with the place. If you list too low, you’ll leave money on the table. A valuation gives you a sensible starting point, so your asking price is based on comparable sales rather than hope.
Responding to low offers
When an offer comes in well below your expectations, it’s natural to feel insulted. A valuation lets you respond calmly. You can say something like, “I’ve had the property independently valued, and the report supports a figure closer to this.” That’s far more persuasive than arguing about your favourite features.
Buyers aren’t always dishonest when they make low offers. Sometimes they simply don’t know the local market, and a report helps them see it too.
Dealing with buyers who want a discount
Some buyers will ask for a reduction after inspections, pointing to minor defects or wear and tear. A valuation that already accounts for the property’s condition gives you a reference point for deciding whether a concession is reasonable or whether you’re being pushed too far.
The Bank Valuation Problem Most Private Sellers Overlook
This is the part many sellers don’t see coming. If the buyer is using a bank or lender, the lender will usually order its own valuation before releasing the loan. That valuation is for the lender’s protection, and it doesn’t always match the price you’ve agreed on.
If the lender’s valuer comes in below the agreed price, the lender may only lend against the lower figure. The buyer then has to find the difference in cash, renegotiate, or walk away. Any of those outcomes can delay or derail the sale.
A pre sale valuation won’t guarantee the lender’s figure, since valuers can and do form different opinions. But it gives you evidence to point to if the numbers come in apart, and it helps you price realistically from the start, which reduces the risk of a shortfall.
Valuation Versus Insurance Replacement Cost: Don’t Mix Them Up
Here’s a distinction that trips up a lot of owners. A pre sale valuation estimates market value, which is what a buyer might reasonably pay for the property. An insurance valuation estimates replacement cost, which is what it would take to rebuild the dwelling if it were destroyed.
The two figures can be very different. A solid older house in a strong suburb might have a high market value, while its rebuild cost could be lower or higher depending on materials, building standards and site access. Land usually counts toward market value but not toward replacement cost, because you don’t rebuild the land.
This matters because a sum insured based on market value can leave you under-insured, and a sale price based on replacement cost will usually miss the market. If you’re selling, make sure you’re asking for the right type of valuation. We prepare both market-based and insurance valuations, so it’s worth being clear about which one you need before you book.
Common Misconceptions About Pre Sale Valuations
“A valuation sets the price”
It doesn’t. A valuation is an opinion of value, and you decide what to list at and what to accept. Buyers are also free to offer whatever they like.
“The valuation guarantees the sale price”
It doesn’t do that either. Market conditions change, buyers have different budgets, and two valuers may land a little apart. Treat the figure as a well-informed range, not a promise.
“You need one for every sale”
For most private sales, a valuation isn’t legally required. It’s a practical tool, not a formal step in the contract process. That said, if the property is part of an estate, a family settlement or a dispute, there may be other requirements, and the rules differ between states and territories.
“Cheaper always means it’s not worth it”
Price matters, but so does the scope of the report. A quick desktop estimate isn’t the same as a full inspection with a written report you can show a buyer or lender. Make sure you know what you’re paying for.
When a Pre Sale Valuation Might Not Be Worth It
To be fair, there are situations where a valuation may not add much. If the property is a low-value home in a very active market where comparable sales are abundant and recent, a local agent’s free appraisal might be enough to get started. If you’re selling a unit with very similar neighbours, you may already have a good sense of the range.
It’s worth weighing the cost against the value of the sale. If the price difference you’re trying to protect is small, a simpler approach might do the job.
Practical Steps Before You Get a Valuation
- Gather your paperwork. Title details, plans, recent renovation records, strata documents if relevant, and any approvals for work done on the property.
- Tidy the property. A valuer will still see the house as it is, but a clean, well-presented home makes it easier to assess accurately.
- Note recent works and defects. Be upfront about anything that needs attention, such as roof repairs or a pest issue. Valuers prefer to know early.
- Check the local market yourself. Look at recent sales on public records and listing sites so you can compare notes with the valuer’s findings.
- Ask about the report format. Make sure you’ll receive a written report you can use in negotiations and share with a lender if needed.
- Speak to your conveyancer or solicitor. Rules around contracts, cooling-off periods and disclosure vary by state and territory; in NSW, a contract must be prepared before the property is advertised, so ask your conveyancer or solicitor what applies to your sale.
Frequently Asked Questions
Do I need a pre sale property valuation to sell privately?
Usually not, but it’s a practical step. It helps you price the property sensibly and gives you evidence to support your position in negotiations.
Will a pre sale valuation help me get a higher price?
It can help you avoid underpricing and support your asking price, but it can’t force a buyer to pay more. What it does is give you a defensible position.
What’s the difference between a pre sale valuation and a bank valuation?
A pre sale valuation is commissioned by you, the seller, to inform your pricing. A bank valuation is ordered by the buyer’s lender to protect the loan. They can produce different figures.
Can the valuer tell me my property’s insurance value?
Not usually as part of a market valuation. Insurance valuations estimate replacement cost, which is a different calculation, so ask for the right service if you need both.
How long does a pre sale valuation take?
It depends on the property and the valuer’s schedule, so check with the valuer when you book. Don’t rely on a timeframe from a generic article.
Conclusion
Selling privately gives you control over the process, but it also means you carry the pricing risk. A pre sale valuation gives you an independent view of market value, helps you set a realistic price and gives you evidence when offers come in low or a lender’s valuation lands unexpectedly. It isn’t a guarantee, and it isn’t always necessary, but for many sellers it’s a sensible investment in a clearer negotiation.
Call for Professional Advice
If you’re selling privately and want an independent view of your property’s value, Australian Insurance Valuations can help. We also prepare building replacement and insurance valuations for owners, strata managers and investors, so we can help you work out which type of valuation fits your situation. Call us on 0438 080 786 to talk through your options.